Federal Reserve Holds Rates Steady, Mortgage Rates Could Rise
On October 28, the Federal Reserve announced that it would keep the federal funds rate unchanged, a decision that aligns with market expectations. This stability in rates is significant for the mortgage market, as it suggests that mortgage rates may not react dramatically in the short term. Currently, the average rate for a 30-year fixed mortgage has decreased slightly to 7.17% APR, according to data from Zillow.
The Federal Reserve's dual mandate focuses on achieving maximum employment and maintaining inflation close to 2%. When inflation rises, the Fed typically increases the federal funds rate, which in turn raises consumer borrowing costs, including mortgage rates. Conversely, if unemployment rises, the Fed may lower rates to stimulate borrowing and hiring.
Market Reading & Resources
Sponsor funding complete. Trade on.
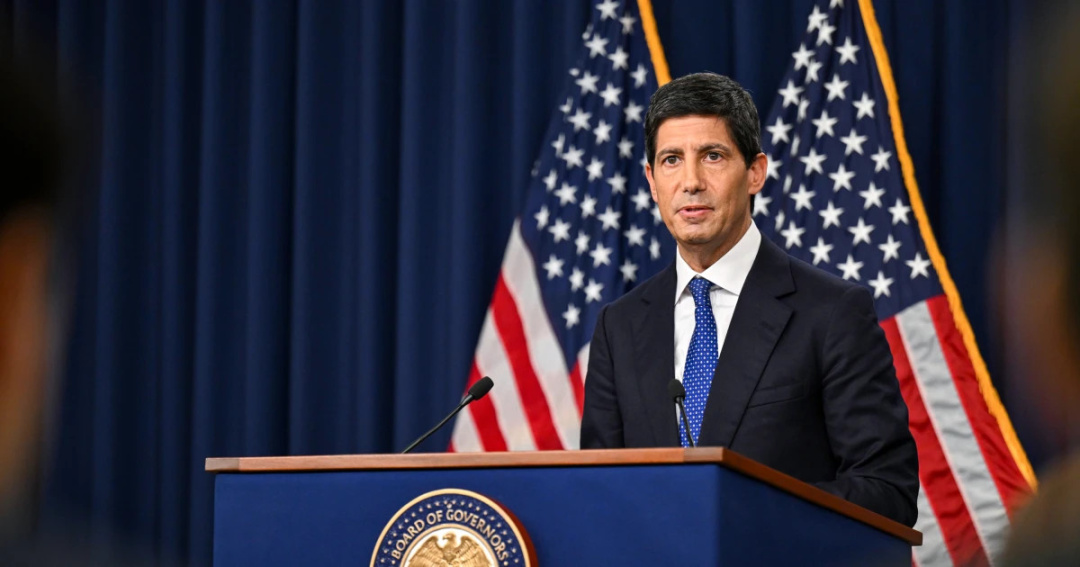
Recent employment data indicates that job growth remains steady, shifting the focus back to inflation as a primary concern. Despite Fed Chair Kevin Warsh's cautious approach leading up to the meeting, market analysts anticipated that the Fed would maintain the current rate following a previous increase.
Upcoming PCE Data May Signal Changes in Mortgage Rates
Looking ahead, mortgage rates may be influenced by the upcoming release of the Personal Consumption Expenditures (PCE) price index, which is the Fed's preferred measure of inflation. This data, set to be released on October 29, could provide insights into inflation trends that the Fed did not have during its recent decision-making process. If the PCE data indicates rising inflation, mortgage rates could increase as lenders adjust to protect their investments.
Mortgage Rates Face Potential Increase Amid Inflation Concerns
In October, the average mortgage rate has been around 7.3%, compared to 6.98% in September. Analysts suggest that if inflation continues to rise, it is plausible that mortgage rates could reach 7.5% by the end of the year, a level not seen since October 2023. The Fed's potential rate hike in December could further influence these rates, as it aims to manage inflation effectively.
Overall, while the Fed's decision to hold rates steady provides some immediate stability, the evolving economic landscape suggests that mortgage rates could fluctuate significantly in response to inflation data and market conditions. As such, prospective homebuyers should remain vigilant about these developments and their potential impact on borrowing costs.