Federal Reserve's Rate Decisions: Inflation and Economic Considerations
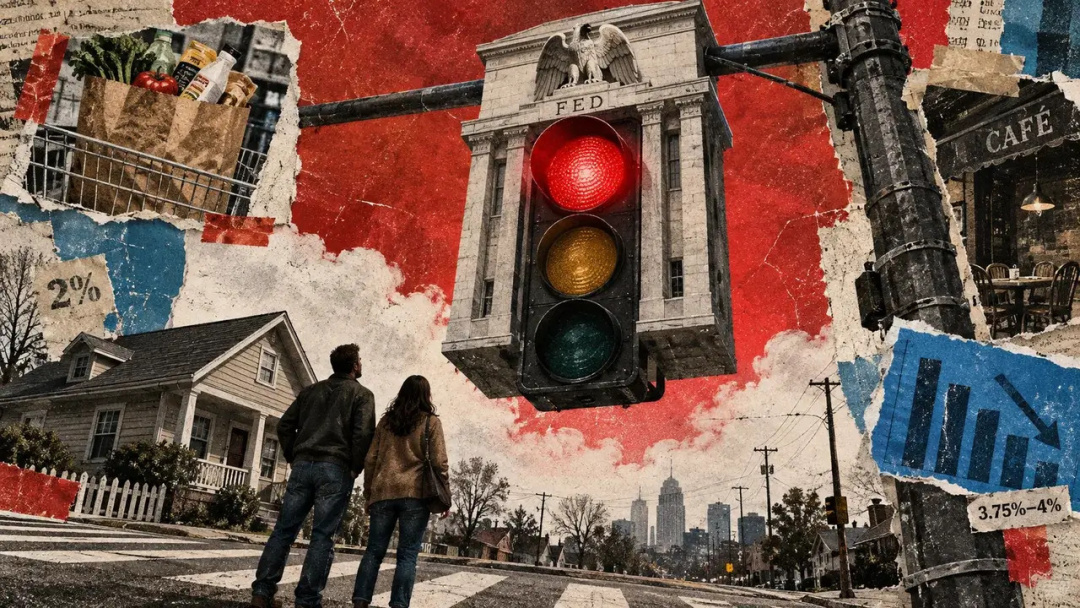
The Federal Reserve can choose to stop raising interest rates before inflation hits the 2% target if officials believe the economy is already moving in that direction without further increases. However, during the September meeting, most officials remained unconvinced, citing strong consumer spending and ongoing price increases that outweighed the economic strain caused by higher borrowing costs.
The minutes from the meeting, released on October 7, outline the rationale behind the unanimous decision to raise the main interest rate to a range of 3.75% to 4%. Many participants anticipated another rate hike by the end of the year, although their motivations varied. Some viewed higher rates as a necessary precaution against persistent inflation, while others believed the economy would require elevated rates regardless.
Market Reading & Resources
Sponsor funding complete. Trade on.
This divergence in perspectives illustrates the complexity of the Fed's decision-making process. Evidence suggesting that temporary price increases are subsiding could reassure those advocating for higher rates as a safeguard. Conversely, officials concerned about robust spending would seek signs of reduced consumer and business expenditure.
The discussions shed light on the conditions that might prevent another rate hike, although there was no consensus on specific criteria. Higher interest rates typically make borrowing more expensive and saving more appealing, which can dampen spending and complicate pricing strategies for businesses. The impact of these rates is not uniform; for instance, while homebuyers may reduce their purchases, companies with ample cash reserves may continue to invest.
The Fed's ability to influence inflation is limited, as it cannot directly address supply shortages that contribute to rising prices. However, by raising borrowing costs, it can reduce overall spending, making it more challenging for businesses to pass on price increases to consumers. In September, officials noted that rising energy costs and substantial investments in artificial intelligence were contributing to inflationary pressures.
Some businesses appeared more capable of transferring their costs to consumers, and several officials pointed to ongoing price increases in services outside of housing. A decrease in fuel prices could alleviate some of these pressures, but sustained consumer spending could still enable businesses to raise prices.
A series of reports indicating slower price increases across various sectors would provide the Fed with additional justification to pause rate hikes. It is important to note that falling inflation rates merely indicate a slowdown in price increases rather than a decrease in prices themselves. Officials would be looking for signs that businesses are losing the ability or incentive to raise prices further.
Moreover, the Fed must differentiate between genuine economic improvement and adjustments to how economic data is measured. The minutes highlighted a planned revision to the inflation calculation that would lower the reported contributions of software prices and investment management fees.
While officials generally believed that inflation expectations would stabilize around the 2% target over time, there were concerns that prolonged periods above this target could lead to demands for higher wages and increased pricing strategies from businesses.
A trend of slower price increases across the economy, coupled with public expectations of declining inflation, would reduce the urgency for officials to raise rates as a precautionary measure. The Fed's dual mandate to support employment also constrains how aggressively it can raise borrowing costs.
In September, participants noted steady employment levels, with relatively few individuals unemployed, and many believed that the job market had strengthened, allowing the Fed some leeway in combating inflation. Some officials indicated that wage growth was sufficient for inflation to return to the 2% target, while others argued that the job market was not currently a driver of inflation.
The dynamics of hiring and layoffs were also discussed, with both being unusually low. While low layoffs can create a perception of a healthy job market for those employed, weak hiring can present challenges for job seekers. If layoffs begin to rise before hiring improves, it could lead to a more concerning employment landscape.
An increase in unemployment alongside broader layoffs would complicate the justification for further rate hikes, even if inflation remained elevated. A single disappointing jobs report might be dismissed as a temporary anomaly, but consistent evidence across multiple reports would carry more weight.
If inflation continues to slow while employment remains stable, the Fed would have a stronger case for pausing rate increases. In September, officials assessed the likelihood of employment performing better or worse than expected as roughly equal, while inflation appeared more susceptible to being too high.
Continued weak hiring or increased job losses would prompt the Fed to reconsider its stance without waiting for a recession to materialize. Many officials expressed the view that current interest rates were not significantly slowing the economy, despite the burden of high mortgage rates and the strain on lower-income households.
While some businesses still have access to borrowing, strong investment in AI and stock market gains are supporting spending among wealthier households. The Fed must evaluate whether combined spending is slowing enough to reduce inflation, recognizing that high borrowing costs in housing do not automatically resolve the decision-making process.
Economists define a neutral interest rate as one that neither accelerates nor decelerates economic growth, but estimating this rate is challenging. Some officials have adjusted their estimates upward, suggesting that a higher interest rate may be necessary to achieve the desired economic slowdown.
If lenders become more cautious and spending decreases, it would provide evidence that current borrowing costs are having the intended effect. Market rates can also rise independently of Fed actions, although longer-term loan rates do not always align with the short-term rates controlled by the Fed.
A scenario of lower inflation alongside stable employment could lead investors to anticipate lower borrowing costs while maintaining interest in volatile assets like Bitcoin. Conversely, if job losses and difficulties in obtaining loans lead the Fed to pause, investors might be compelled to liquidate assets to maintain liquidity.
Maintaining steady rates does not guarantee future cuts or a return to cheap financing. The Fed's next meeting is scheduled for October 27-28, and the minutes released provide insight into their September deliberations. Evidence of slowing price increases without additional rate hikes would support a pause, while rising job losses would complicate the case for further increases, leaving little for Bitcoin investors to celebrate.