Euro Zone Business Activity Reaches Highest Growth in Over Three Years
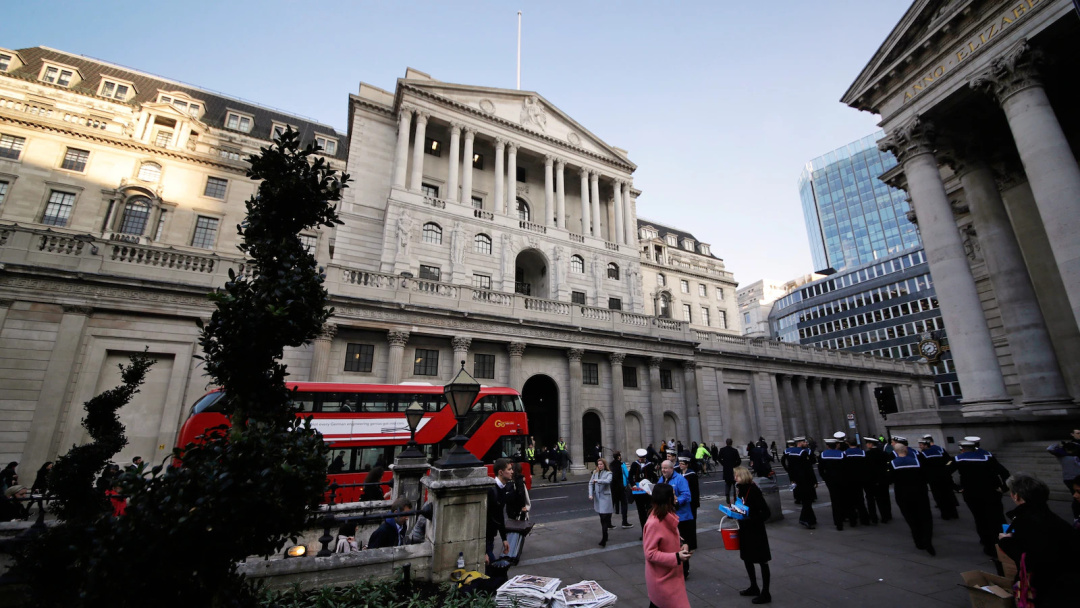
Euro zone business activity saw a notable expansion in September 2026, marking the fastest growth in nearly three and a half years. This surge in demand occurred despite ongoing inflation concerns, particularly those arising from the conflict in the Middle East. According to a private survey, inflation within the Euro zone increased unexpectedly to 3.8% in September, up from 3.2% in August, primarily driven by soaring energy costs. This rise in inflation raises the possibility that the European Central Bank (ECB) may consider increasing interest rates more aggressively than previously anticipated.
Despite the inflationary pressures and a recent uptick in bond yields, business activity has remained resilient. The S&P Global Eurozone Services PMI rose to a 10-month high of 53 in September, up from 51.6 in August, aligning with preliminary estimates. The composite index, which combines both services and manufacturing sectors, also increased to 53.1 from 52 in August, representing the highest level since April 2023 and indicating the strongest quarterly performance since the second quarter of 2022. A PMI reading above 50 signifies growth.
Market Reading & Resources
Sponsor funding complete. Trade on.
Chris Williamson, chief business economist at S&P Global Market Intelligence, noted that the collective signals from the PMI surveys suggest a quarterly GDP growth rate of 0.4%, with momentum expected to accelerate as the Euro zone approaches the fourth quarter. He highlighted that while growth drivers vary across countries, IT-related services are experiencing particularly robust growth, bolstered by investments in artificial intelligence and supported by advancements in professional and commercial services.
Spain emerged as the strongest performer in the Euro zone, followed closely by Ireland. Germany's recovery has also gained momentum, reaching one of its strongest rates since early 2022, while Italy and France recorded more modest growth figures.
The survey indicated that services firms experienced a faster growth rate in new business, a critical indicator of demand, with export orders finally breaking a streak of 39 months of contraction. This was complemented by the most significant increase in factory orders since early 2022, leading to an overall rise in new orders at the fastest pace in 41 months. Notably, foreign demand surged, with overseas orders increasing at the quickest rate in over four and a half years.
However, a slowdown in hiring within the services sector counterbalanced a slight uptick in factory job creation, resulting in overall employment growth being weaker than expected. Despite this, business confidence remained stable.
The survey also revealed intensifying inflation pressures, with both input and output prices rising at their fastest pace in four months. Williamson remarked that the renewed upturn in price pressures suggests that Euro zone inflation may be trending closer to 4%, significantly above the ECB's target of 2%. This combination of accelerating growth and rising inflation is likely to fuel speculation regarding more aggressive monetary policy tightening by the ECB. Currently, markets are pricing in the likelihood of more than two interest rate hikes by the ECB by mid-next year.