Lorie Logan Advocates for Voluntary Central Clearing at Federal Reserve
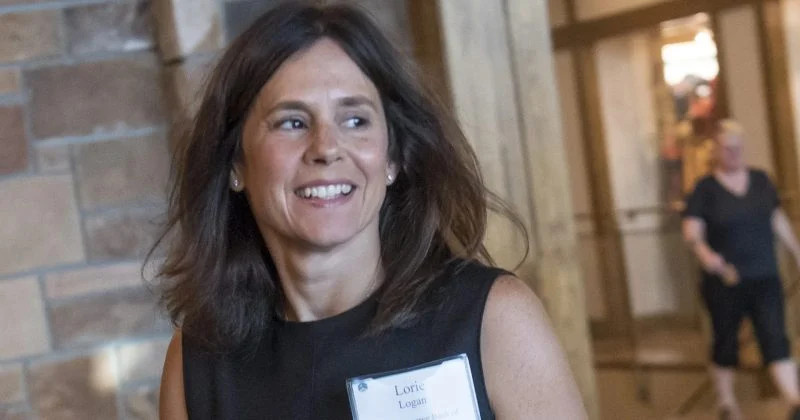
Lorie Logan, President and CEO of the Federal Reserve Bank of Dallas, has made a compelling case for the Federal Reserve to voluntarily adopt central clearing for its open market operations. During a conference on market liquidity hosted by the New York Fed on July 9, Logan argued that this approach could enhance efficiency, resilience, and liquidity in the financial system, particularly as the Securities and Exchange Commission (SEC) pushes private-sector participants toward similar practices.
The SEC's central clearing mandate, finalized in December 2023, requires private-sector Treasury repo participants to clear their trades through the Fixed Income Clearing Corp (FICC). However, this mandate does not extend to the Federal Reserve. Logan suggests that the Fed should opt in voluntarily, routing its repo and reverse repo operations through the same clearinghouse infrastructure that will soon be mandatory for others.
Market Reading & Resources
Sponsor funding complete. Trade on.
Logan outlined several benefits of central clearing, including reduced counterparty intermediation costs through netting, which would alleviate the burden on dealer balance sheets. This shift could also improve liquidity provision during market stress, a critical factor during turbulent times. Additionally, it would enhance the Fed's influence over the Secured Overnight Financing Rate (SOFR), which has become the benchmark replacement for LIBOR in numerous financial contracts.
The call for broader central clearing in Treasury markets is not new; it stems from the market disruptions experienced in 2019 and 2020. The chaos in the repo market in September 2019, when overnight lending rates surged to nearly 10%, revealed significant structural vulnerabilities. The subsequent Treasury market turmoil in March 2020, triggered by the onset of COVID-19, further underscored the need for reform.
Logan has been advocating for this shift for over a year, co-authoring a paper in September 2025 that explored pathways for modernizing the Federal Open Market Committee's operational framework in light of evolving clearing practices. Her recent remarks mark a significant public endorsement of the Fed's potential participation in a cleared ecosystem.
The SEC's phased mandate for central clearing of cash Treasury operations is set to conclude by June 30, 2027. Since the SEC's ruling, centrally cleared repo volumes have been on the rise, indicating that the industry is adapting ahead of schedule.
Logan's proposal also addresses the institutional dynamics at play. If all major private-sector counterparties are required to clear through FICC while the Fed operates on a separate bilateral track, it could lead to a fragmented system that undermines the effectiveness of the Fed's monetary policy tools, including repo operations and standing facilities.
For traditional fixed-income investors, the implications of the Fed adopting voluntary central clearing are clear. It could narrow spreads in the repo market by reducing the balance sheet costs that dealers incur when facilitating transactions between the Fed and the broader market.
However, there are risks to consider as well. Concentrating more activity through FICC could increase systemic risk within a single entity, a concern that has been highlighted by the Financial Stability Board as a potential vulnerability in global markets. Logan's advocacy for voluntary central clearing reflects a proactive approach to enhancing the stability and efficiency of the financial system while navigating these complexities.