Federal Reserve Rate Hike Pressures Crypto Lending Yields
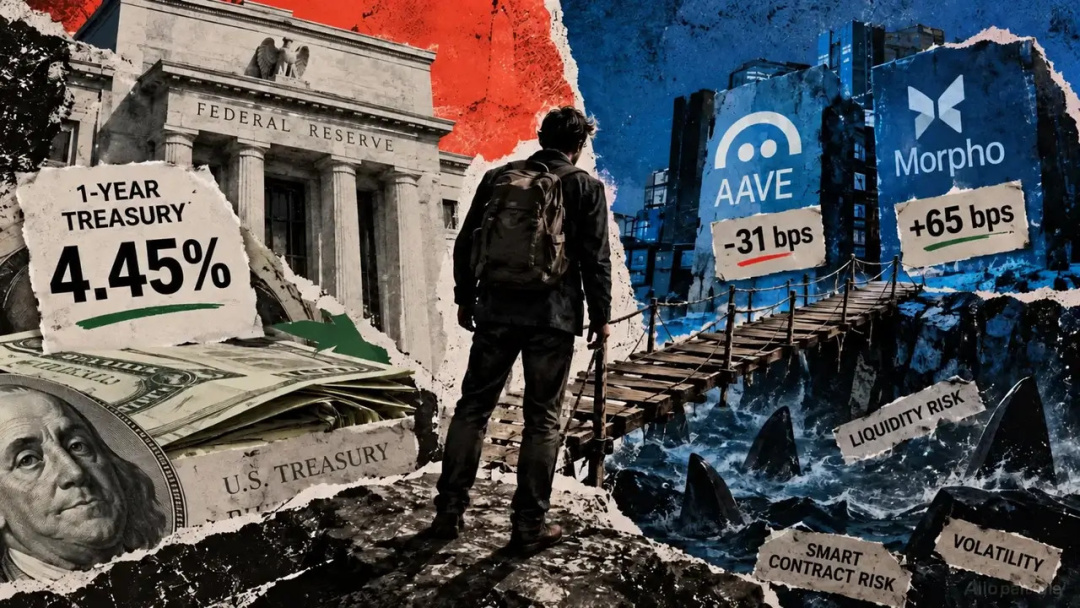
On September 16, the Federal Reserve raised its target interest rate range by 25 basis points to 3.75%-4.00%. This decision has pushed the one-year Treasury yield to 4.45%, creating a new benchmark for crypto lending yields. As a result, investors are now faced with a choice between the relative safety of government debt and the risks associated with crypto lending.
Analysis from Coin Metrics indicates that USDC lenders on Aave earned an average of 31 basis points less than the one-year Treasury yield during the period studied in 2026. Notably, the Aave yield fell short of the Treasury rate in 78% of the intervals measured. This gap existed prior to the Fed's decision, raising questions about the future impact of such rate hikes on crypto lending yields.
Market Reading & Resources
Sponsor funding complete. Trade on.
Anthony DeMartino, co-founder and CEO of Sentora, suggests that the Canadian Dollar Offered Rate (CDOR) is a more relevant benchmark for assessing on-chain credit than the Secured Overnight Financing Rate (SOFR). DeMartino argues that the correlation between SOFR and CDOR has been low, indicating that a Fed rate hike may not significantly affect on-chain rates. The one-year Treasury serves as a measure of opportunity cost for investors choosing crypto lending over safer alternatives, while CDOR reflects the daily borrowing costs within Aave.
A recent working paper from the European Central Bank highlights the weak and unstable transmission of monetary policy into decentralized finance (DeFi) stablecoin deposit rates in the short term. It notes that rates can sometimes move contrary to Fed policy before eventually converging over a longer period. This divergence is often driven by deleveraging in crypto markets, which reduces the organic demand that influences on-chain borrowing costs.
Current data from Coin Metrics shows that Aave's USDC yield is trailing the one-year Treasury by an average of 31 basis points. In contrast, Morpho's median USDC vault has outperformed the Treasury benchmark by 65 basis points, albeit with approximately 3.3 times the annualized volatility of Aave's yield. The premium over CDOR compensates for risks associated with smart contracts, liquidity, and credit, but there is no universal rate applicable across the board.
DeMartino suggests that a plain stablecoin vault should ideally yield at least the higher of the Treasury rate or CDOR plus an additional 100 to 300 basis points. More complex strategies may require yields of 300 to 600 basis points above that baseline. This analysis illustrates why a 4.1% yield may seem inadequate compared to the 4.45% offered by Treasuries, and even a 5.1% crypto yield can be questionable when considering volatility and tail risks.
Kraken's newly introduced xStocks Vaults allow investors to maintain exposure to tokenized equities while borrowing stablecoins against that collateral to invest in DeFi strategies. Currently, Kraken advertises a 2% net annualized yield for SPYx and QQQx tokens, and 1.8% for NVDAx, after accounting for a 25% performance fee. Withdrawals may take up to three days or longer during periods of market stress.
DeMartino explains that if the underlying stock sells off, the smart contract will automatically repay the debt to prevent liquidation. Conversely, if the market rises, the contract will take on more debt to maintain yield. A specific 2% loss from the crypto vault's strategy could negate the entire year's additional return, highlighting the importance of distinguishing between risks associated with the vault and those inherent to the equity tokens themselves.
The optimistic scenario hinges on sustained organic borrowing demand, primarily in Bitcoin, which could drive CDOR higher independently of Fed actions. In this case, crypto lending yields could surpass Treasury rates due to genuine on-chain demand. Conversely, a prolonged period of high interest rates from the Fed could dampen risk appetite, leading to reduced crypto activity and forcing borrowers to deleverage. In such a scenario, stablecoin deposit rates may decline even as Treasury yields remain elevated, compressing the yields that investors receive from crypto lending.
Ultimately, while crypto yield products are readily accessible, the critical question remains whether the yields adequately compensate for the underlying risks. No single benchmark, whether CDOR or Treasury, can fully address this complex issue.