Central Banks Prepare for Key Rate Decisions Amid Inflation Pressures
Three major central banks are poised to announce important policy decisions within a span of 72 hours, as inflationary pressures intensify due to the ongoing US-Iran conflict and volatile bond markets. The Federal Reserve will kick off this series of announcements on September 16, followed by the Bank of England on September 17 and the Bank of Japan on September 18. This comes at a time when oil prices have surged above $100 per barrel, and bond yields are reaching levels not seen in nearly two decades.
The resurgence of global inflation has been significantly influenced by the US-Iran conflict, which has disrupted energy supply chains. Brent crude oil has risen to $108 per barrel, impacting consumer price data across major economies.
Market Reading & Resources
Sponsor funding complete. Trade on.
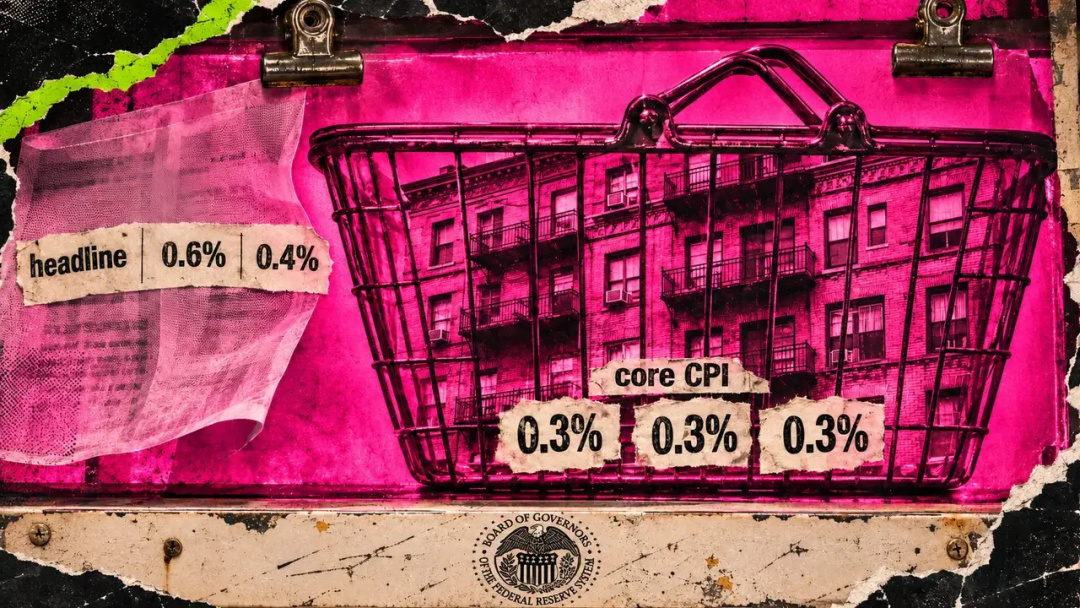
Market analysts are anticipating a high likelihood that the Federal Reserve will implement a 25 basis point rate hike on September 16, marking its first increase since the onset of pandemic-related monetary easing. This expectation is largely driven by August's core Consumer Price Index (CPI) reading, which exceeded forecasts.
In the UK, the Bank of England maintained its policy rate at 3.75% during its last meeting in July, but the decision was contentious, with a 6-3 vote indicating significant internal divisions regarding future rate hikes. Ten-year gilt yields have approached 5.4%, the highest in decades, with inflation projected to surpass 3% by 2026, largely due to the same energy price increases affecting other economies.
Meanwhile, the Bank of Japan is expected to raise its policy rate from 1.00% to 1.25% on September 18, which would be its second increase in 2026. The recent strong wage growth in Japan provides the Bank of Japan with the justification needed to continue normalizing its policy after years of maintaining negative interest rates and yield curve control.
Japanese investors, who are significant holders of foreign bonds, particularly US Treasuries and European sovereign debt, may respond to rising domestic rates by reallocating their investments, potentially increasing selling pressure in already volatile global bond markets.
The current yields on US Treasuries nearing 5% and UK gilts at 5.4% reflect a fundamental repricing of sovereign debt, which has implications for mortgage rates and corporate financing costs. In the realm of digital assets, Bitcoin and other cryptocurrencies are facing mixed signals. While higher real yields generally pose challenges for non-yielding assets, Bitcoin has occasionally been viewed as an inflation hedge. The last time Treasury yields approached these levels, Bitcoin experienced a rally that led to new highs.
The ongoing US-Iran conflict shows no signs of de-escalation, raising concerns that oil supply disruptions may continue or worsen. Should Brent crude prices exceed $110 or $120 per barrel, central banks will face increasingly difficult decisions between combating inflation and preventing recession.