US Equities Surge as Softer Producer Prices Ease Rate Hike Concerns
US equities climbed on August 13 after the Bureau of Labor Statistics reported that July's Producer Price Index (PPI) came in softer than anticipated. The S&P 500 rose approximately 0.5% to 0.7%, reaching an intraday record near 7,817, while the Nasdaq Composite outperformed with gains of about 0.8% to 1.0%. The technology and communication services sectors led the market rally.
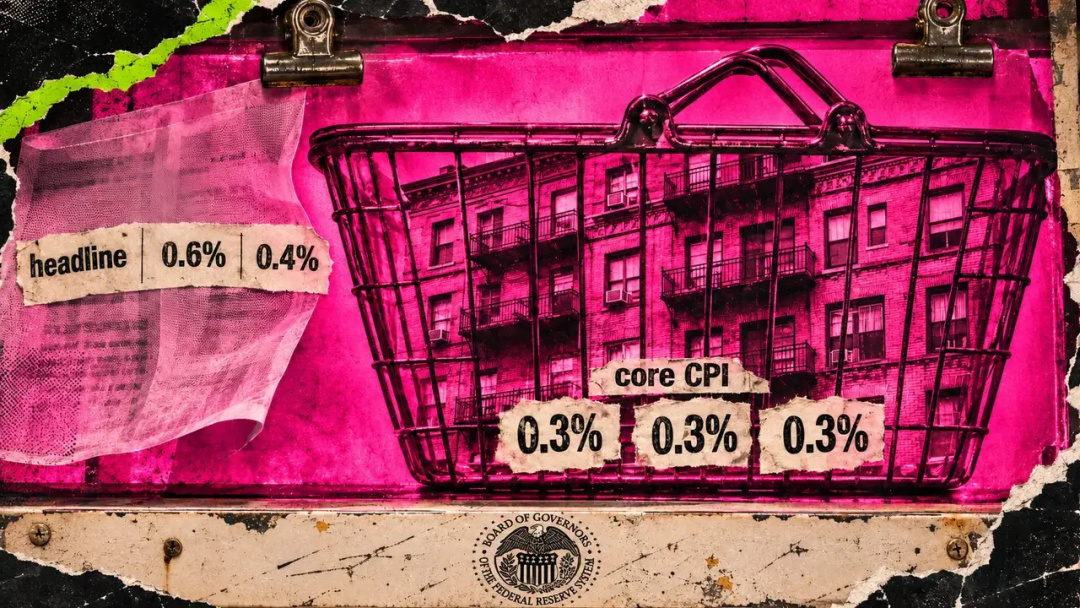
The July PPI reading was flat month-over-month and showed a year-over-year increase of 4.7%. Economists had expected a 4.9% annual increase, while June's reading was notably higher at 5.5%. This data came just a day after the July Consumer Price Index (CPI) also indicated easing inflation, with a 3.4% yearly increase and core inflation at 2.5%, down from 2.6% the previous month.
Market Reading & Resources
Sponsor funding complete. Trade on.
For traders, the implications were clear: the Federal Reserve is likely to keep interest rates unchanged at the upcoming September 15-16 FOMC meeting. The CME FedWatch Tool reflected this sentiment, showing increased bets on no rate change following the release of the PPI data.
Currently, the federal funds target range is set between 3.50% and 3.75%, a level maintained since the July 28-29 FOMC meeting. This decision was not unanimous, as three committee members voted against holding rates steady, indicating some division within the Fed regarding future monetary policy.
The Federal Reserve has kept rates within this range since December 2025, as officials have struggled with inflation rates consistently exceeding the 2% target for over five years. A minority within the FOMC has called for a rate hike to combat persistent inflation, but recent economic indicators, particularly a weaker-than-expected jobs report, have tempered immediate expectations for such actions.
Technology and communication services stocks were the standout performers during this trading session. The technology sector, especially companies involved in artificial intelligence, has shown a heightened sensitivity to shifts in rate outlooks, often leading market trends when inflation concerns ease and borrowing costs appear stable.
Despite the positive market response, some traders remain cautious. While a hold on rates in September seems increasingly likely, there are concerns about the potential for a rate increase later in 2026, as both the year-over-year PPI at 4.7% and CPI at 3.4% remain above the Fed's long-term target of 2%.