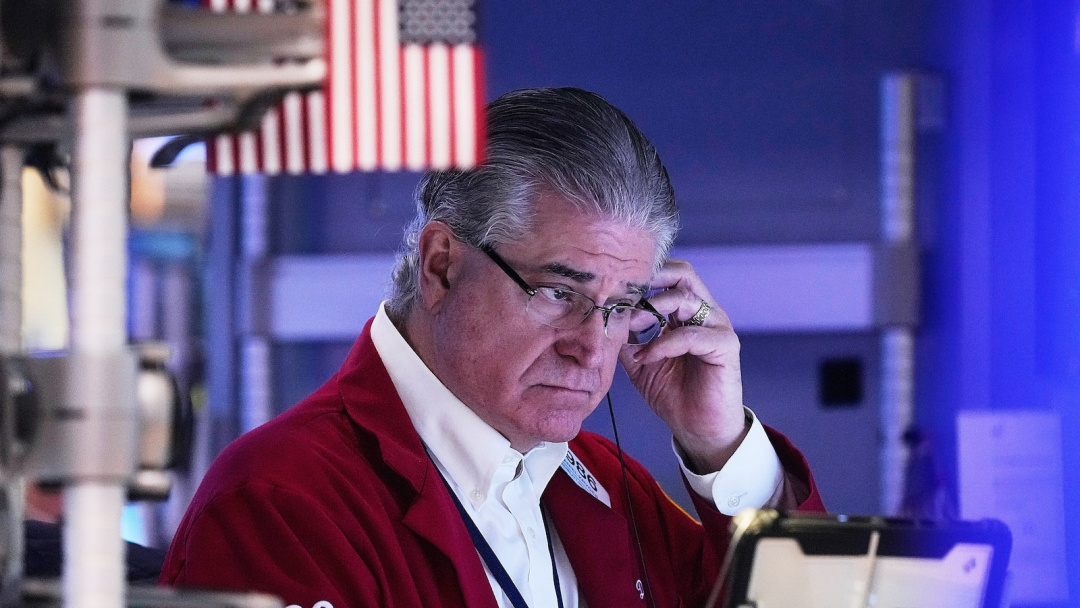
Market Warning Signals Intensify Amid Inflation and Tech Concerns
Market warning signals are becoming increasingly pronounced as investors navigate high oil prices and ongoing geopolitical tensions. Although oil prices have dipped from the $100 mark, they remain elevated enough to pose inflation risks, which in turn keeps long-term government borrowing costs high. This situation typically signals trouble for risk assets, particularly in the tech sector, where the once-unstoppable rally in AI-related stocks is now facing skepticism regarding profitability and cash flow. Concerns are growing as semiconductor stocks, which have driven much of the tech sector's gains, begin to falter amid fears of oversupply.
As tech earnings reports roll in, investors are closely scrutinizing revenue and profit figures to determine if they justify the significant investments in AI technology. With expectations of U.S. rate hikes this year, yields on AI hyperscaler bonds are rising faster than those on Treasuries, and the cost of hedging against credit deterioration has surged. This has led to a notable decline in bullish positions on Nasdaq futures, which are at a 17-year low, indicating that many investors are moving away from tech stocks, potentially creating room for future investment.
Market Reading & Resources
Sponsor funding complete. Trade on.
The equity market's bull run is increasingly supported by record levels of debt. Margin debt, which reflects the amount investors borrow to invest, reached a staggering $1.5 trillion in June, resulting in a $1 trillion deficit in investors' net balances with brokers for the first time. This situation heightens the likelihood that investors who owe more than they possess in cash will sell off stocks during market declines rather than buy more.
U.S. 30-year Treasury yields have remained above 5% for an extended period, the longest since the early financial crisis of 2007. While this level alone may not trigger a market selloff, higher long-term rates can increase borrowing costs for loans, including mortgages, which could affect consumer spending and complicate economic policies ahead of the upcoming midterm elections.
Raymond James Chief Investment Officer Larry Adam noted that spreads on some of the riskiest corporate bonds have reached a 15-month high, indicating that investors are demanding greater compensation for lending to weaker borrowers. This trend reflects a growing caution among investors as they adjust to tighter Federal Reserve policies and a more challenging environment for lower-rated corporate debt.
Despite oil prices retreating from their peak, they remain 27% higher year-on-year, benefiting U.S. producers while straining consumers in Europe and the UK, where import costs have surged nearly 30%. The situation is even more dire for countries like Japan, which is experiencing record-high import costs due to a weakened currency. Indian refiners are facing a 40% increase in Brent-linked crude prices, while Argentinian and Turkish refiners are paying nearly 50% more. Additionally, shipping costs have skyrocketed, with tanker rates for key routes to Asia from the Middle East increasing by around 600% year-on-year.
The Japanese yen has fallen to nearly 164 per dollar, marking a four-decade low, prompting concerns about potential intervention by Japanese authorities. Despite reports of the Bank of Japan considering a faster pace of rate hikes, the yen remains under pressure due to low domestic rates and the ongoing energy crisis. The yen's status as a favored funding currency for carry trades—where investors borrow in yen to invest in higher-yielding assets—adds to the volatility. A sudden appreciation of the yen due to intervention could force investors to quickly unwind their positions, reminiscent of market reactions seen in August 2024.