Analysts Forecast Recovery for AI Stocks in 2027 Amid Market Adjustments
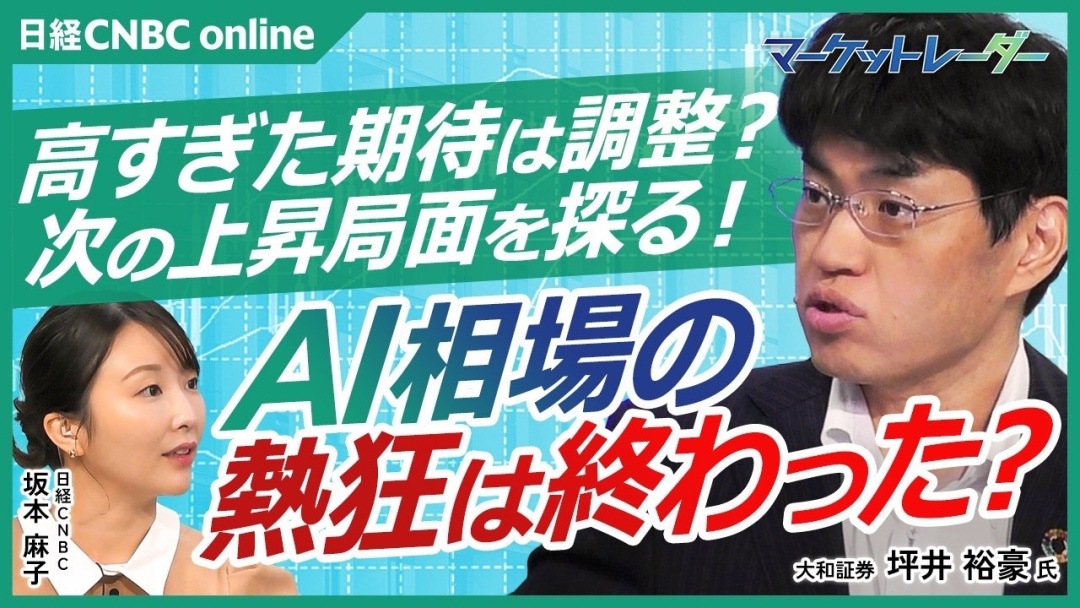
Artificial intelligence stocks are expected to regain momentum in the second half of 2027, according to Yugo Tsuboi, a strategist at Daiwa Securities. He suggests that the recent selloff in the market represents a necessary adjustment rather than the onset of a prolonged downturn in AI investment. Tsuboi notes that excessive market expectations are beginning to ease, allowing investors to better assess the implications of tighter U.S. data center regulations.
The sharp decline in U.S. equities observed on November 5 was primarily attributed to trading positions and risk management strategies rather than any fundamental economic problems. Tsuboi explains that the selloff was influenced by a combination of value-at-risk-driven investment strategies, rebalancing by leveraged exchange-traded funds, and concerns regarding market liquidity.
Market Reading & Resources
Sponsor funding complete. Trade on.
Since the summer, technology-focused long-short funds have been experiencing weaker returns, particularly as semiconductor stocks underwent corrections. Increased market volatility prompted some investors to accelerate profit-taking, resulting in additional selling as funds adjusted their exposure to adhere to risk limits. Tsuboi highlights that leveraged ETFs may have exacerbated market fluctuations through automatic portfolio adjustments.
Despite the downturn, Tsuboi emphasizes that it does not resemble a broader financial crisis. In a genuine liquidity shock, investors typically sell even traditionally safe assets to raise cash, leading to disruptions across multiple markets. However, during the November selloff, interest rates remained stable, and there was little evidence of widespread selling of safe-haven assets, indicating that the turbulence was largely confined to equity positioning.
Tsuboi points to the VIX volatility index and its futures term structure as critical indicators of market stabilization. When short-term volatility expectations exceed long-term expectations, a condition known as backwardation, it typically signals elevated market stress. A return to a more normal futures structure would suggest that selling pressure is subsiding.
The recent correction has also led to a reduction in the unusually high expectations embedded in AI-related stock valuations. In Japan, the Nikkei 225 index has significantly outperformed the broader TOPIX index since around April, reflecting investor enthusiasm for semiconductor manufacturers, AI infrastructure providers, and data center-related companies. However, the gap between these two indexes has narrowed, indicating that investors are reassessing the long-term earnings potential of AI-associated businesses.
Tsuboi argues that stock prices had previously incorporated expectations for developments several years into the future, rather than simply reflecting earnings prospects for 2026 and 2027. The recent adjustment has brought valuations closer to levels that align with more sustainable growth assumptions.
Nevertheless, a prolonged slowdown in AI investment could have repercussions that extend beyond financial markets. The International Monetary Fund has examined various potential outcomes for AI development, including scenarios where investment accelerates alongside productivity improvements or where investor expectations collapse, triggering a market correction. Under a pessimistic scenario, global economic output in 2027 could fall approximately 1% below baseline projections, potentially reducing the growth rate to around 2.4%.
Tsuboi considers such an extreme outcome unlikely, suggesting that AI-related infrastructure investment is more likely to experience a moderate slowdown rather than a complete reversal. He believes that the outlook falls between the IMF scenarios involving supply constraints and a sharper collapse in expectations, leaning closer to the more moderate case.
Political Resistance to Data Center Expansion Raises Industry Concerns
One significant uncertainty facing the industry is the growing political resistance to the rapid expansion of data centers in the United States. Following the November 2026 midterm elections, several newly elected Democratic governors have advocated for restrictions on new facilities, citing concerns over electricity consumption, infrastructure costs, environmental pressures, and the distribution of economic benefits.
Tsuboi highlights the differences in proposals among states like Texas, Ohio, and Georgia. In Texas, a proposed approach would suspend approvals for new data centers until the state legislature establishes appropriate protections. This policy would be particularly restrictive for new developments, although previously approved facilities may not be affected. Ohio's approach is more conditional, allowing new data centers to proceed if developers meet specific requirements related to electricity costs and labor protections.
Georgia has also seen proposals for temporary restrictions on new data center construction, although Tsuboi notes that the incoming governor has previously supported data center development, suggesting that a comprehensive prohibition may not be the intended outcome. The political composition of state legislatures could further limit the implementation of restrictive policies, as Republicans control at least one legislative chamber in each of the three states discussed.
Consequently, Tsuboi anticipates that regulatory pressure will lead to a cooling-off period rather than a complete halt in U.S. data center investment. He points to Singapore as a potential model for how such restrictions could evolve, as the city-state introduced a moratorium on new data center development in 2019 due to resource limitations. However, authorities later developed more selective approval procedures that balanced environmental considerations with the need to remain competitive in the digital economy.
Geopolitical competition also plays a crucial role in the future of American AI investment. The race between the United States and China to develop advanced AI technologies has intensified, with patent activity indicating China's growing capabilities. While the U.S. remains a leader in key areas of AI development, Tsuboi warns that significantly reducing investment could allow China to close the technological gap or surpass American competitors.
The economic security implications of AI infrastructure have made it a priority for investment, complicating the prospect of abandoning large-scale development. Additionally, Tsuboi notes the changing distribution of economic gains between labor and capital, as improvements in productivity associated with cloud computing and automation increasingly benefit companies rather than workers.
For investors, this creates a dilemma. While selling all AI-related holdings may mitigate exposure to short-term market volatility, it could also mean missing out on long-term financial gains from technological advancements. Tsuboi argues that maintaining some exposure to AI-related investments remains important, even as valuations undergo further adjustments.
Historical Trends Suggest Potential Recovery for AI Stocks Post-Elections
Historical market performance following U.S. midterm elections provides grounds for cautious optimism. Tsuboi examined previous periods where a Republican president faced a Democratic-controlled Congress, finding that stock prices rose by an average of approximately 20% over the following 160 trading days. He suggests that divided government does not necessarily produce unfavorable stock market conditions, as political constraints can encourage more moderate policies and reduce the risk of abrupt changes.
The immediate outlook for AI-related equities remains uncertain as investors await clearer indications of how U.S. data center regulations will evolve. Tsuboi expects gradual market advancement through the remainder of 2026 and into early 2027, with political and regulatory uncertainties continuing to weigh on sentiment. A more substantial recovery could begin in the latter half of 2027 as expectations for AI investment improve and the Federal Reserve potentially adopts a more accommodative monetary policy. Overall, Tsuboi envisions a period of slower, sustainable gains followed by a stronger acceleration later in the year, with AI stocks undergoing a temporary cooling-off phase rather than entering a lasting decline.